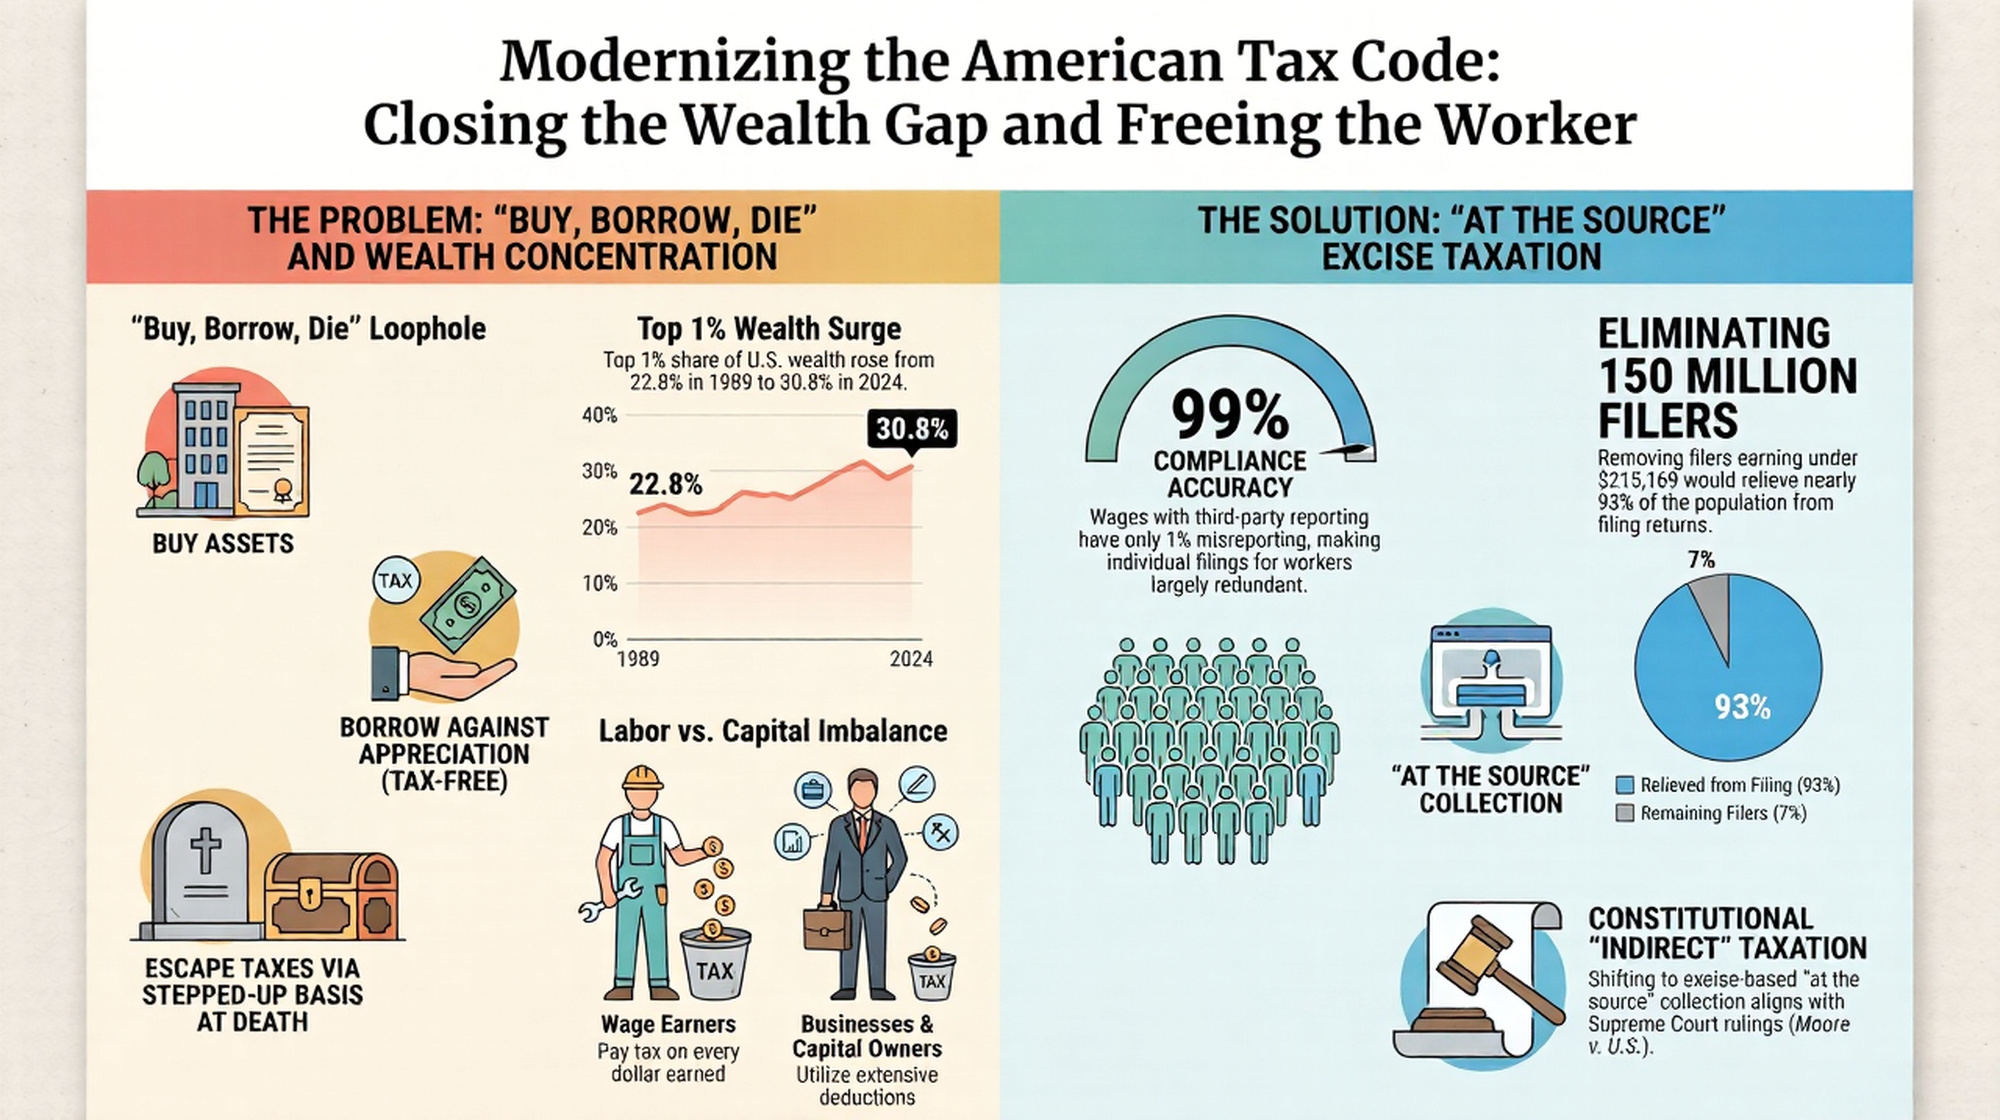
Eliminate the Income Tax on Wages
Wage earnings are subject to both direct and indirect taxes. The IRS classifies the personal income tax on wages as because these taxes cannot be shifted to others, while classifying SSA and FICA taxes as taxes, because these taxes can be shifted to payroll and employment costs.
In , the Supreme Court reaffirmed that Congress’s power under Art. I, §8, cl. 1 of the United States Constitution grants a broad power of indirect taxation, including excises, imposts, duties, and income taxes. Prior to the 16th Amendment, the ability to was considered an essential feature and a fundamental right!
The Proposal
This proposal seeks to eliminate income taxes on wages and earnings while retaining indirect taxes, such as the Social Security and Federal Insurance Contributions Act, intact and in force.
- Eliminate federal individual income tax on wages and salary income.
- Reduce or eliminate the filing requirement for many wage-earning households.
- Retain payroll taxes that finance Social Security and Medicare.
- Simplify tax compliance and reduce time spent on recordkeeping and tax preparation.
- Refocus federal revenue collection toward income sources not derived from ordinary wages.
This proposal would eliminate tax filings for 137.8 million filers, which is the majority of tax filers, while using the income tax as a means to capture the creation wealth with those who make billions. Personal income tax on wages lack the feature to the tax and low incomes tend to burden the economy with government assistance programs and tax credits. This proposal aim is to reduce the tax burden and administrative burden associated with labor income while preserving a stable, fair, and just federal revenue system.